Lottery Lump Sum vs Annuity: Which Payout Option Is Better?
Every time a jackpot climbs into the hundreds of millions, the lottery lump sum vs annuity question starts trending: should a winner take the lump sum or the annuity? The advertised jackpot is almost never the amount a winner actually receives, and the choice between the two payout options can be worth tens of millions of dollars. Here is how both options really work, so you understand the math long before you ever need it.
Table of Contents
How Lottery Payouts Work
When you see a headline jackpot — say, $500 million — that number is the annuity value: the total paid out if the winner chooses to receive the prize as a series of payments spread over decades. Almost every major lottery, including Powerball and Mega Millions in the United States, gives jackpot winners two choices.
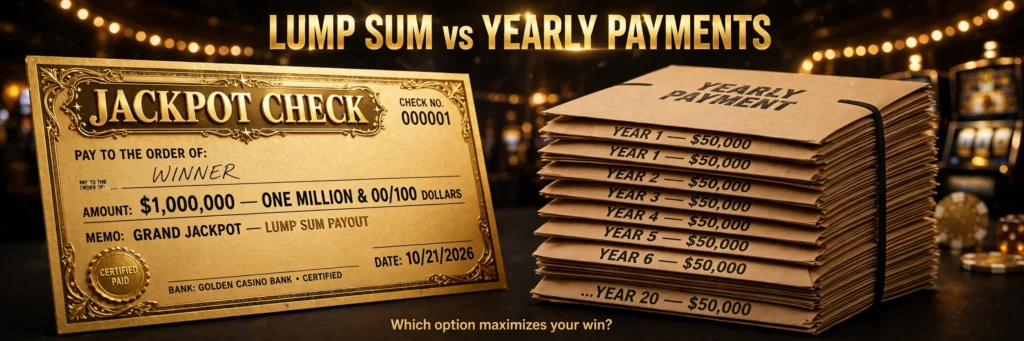
The Lump Sum (Cash Option)
The lump sum is a single payment made shortly after you claim the prize. It equals the present cash value of the jackpot — the amount of money the lottery would need to invest today to fund all the annuity payments. In practice, the cash option is typically around 50% to 60% of the advertised jackpot, though the exact percentage shifts with interest rates. When rates are high, the cash value is a larger share of the advertised amount; when rates are low, it shrinks.
Take a $100 million advertised jackpot as an illustration. The lump sum might be roughly $55–60 million before taxes. After federal and state taxes, the amount that actually lands in your bank account is considerably less — more on taxes below.
The Annuity
The annuity pays the full advertised jackpot in a series of annual payments, usually 30 graduated payments over 29 years. Each payment is about 5% larger than the previous one, a design meant to keep pace with inflation. If you win a $100 million jackpot and choose the annuity, you receive the entire $100 million over three decades — not a discounted amount.
One detail many people miss: if the winner passes away before all payments are made, the remaining payments go to the winner’s estate or designated beneficiaries. The money is not lost.
Lottery Lump Sum vs Annuity: Side-by-Side Comparison
| Lump Sum (Cash) | Annuity | |
|---|---|---|
| What you get | ~50–60% of the advertised jackpot, paid at once | 100% of the advertised jackpot, paid over ~30 years |
| Number of payments | One | 30, each about 5% larger than the last |
| Tax timing | All taxed in a single year, at the top rate | Each payment taxed in the year received |
| Best for | Confident investors who want control and flexibility | People who want guaranteed income and protection from overspending |
| Biggest risk | Spending or investing it badly | Future tax increases; money tied up for decades |
| Estate planning | Full control — gift, invest, or bequeath as you wish | Remaining payments pass to your estate |
Taxes: The Part Nobody Celebrates
Taxes are where the lump sum takes its biggest hit. In the United States, lottery winnings are taxed as ordinary income:
- The IRS automatically withholds 24% of winnings over $5,000, but that is only a down payment — large jackpots are ultimately taxed at the top federal rate of 37%.
- Most states add their own income tax on top, ranging from 0% to over 10%. A handful of states — including Texas, Florida, Washington, Tennessee, Nevada, Wyoming, South Dakota, Alaska, and New Hampshire — do not tax lottery winnings at the state level. (California taxes most gambling income but specifically exempts its own lottery winnings.)
- A large lump sum lands entirely in one tax year, so nearly all of it is taxed at the highest marginal rate. Annuity payments are taxed year by year, which can keep some of each payment in lower brackets — though at jackpot scale, each payment is still large enough to face high rates.
Using our illustrative $100 million example in a no-state-tax jurisdiction: a ~$58 million lump sum minus ~37% federal tax leaves roughly $36–37 million in hand. The “$100 million win” is real, but the spendable amount is far smaller. Knowing this in advance prevents an ugly surprise.
Note: This is general information, not tax advice. Tax law changes, and your actual liability depends on your total income, deductions, and state. Any real winner should hire a tax professional immediately.
Lottery Lump Sum vs Annuity: Which Option Do Most Winners Actually Choose?
The large majority of jackpot winners choose the lump sum. The reasoning is straightforward: they would rather control and invest the money themselves than leave it with the lottery for 30 years. A disciplined investor earning a solid long-term return can end up with more total wealth from the invested lump sum than the annuity would ever pay.
But “disciplined” is doing all the work in that sentence. Studies of lottery winners consistently show that sudden wealth is hard to manage — the annuity exists precisely because a guaranteed check every year for 30 years is a powerful guardrail against the most common way lottery money disappears: too fast, all at once.
How to Decide: A Practical Framework
There is no universally correct answer in the lottery lump sum vs annuity debate. Here is how to think about it:
Consider the lump sum if you:
- Have experience managing or investing significant money (or will immediately hire professionals who do)
- Are younger, giving investments decades to compound
- Want flexibility — to start a business, buy property, or help family on your own timeline
- Understand that you will need the discipline to not spend the principal
Consider the annuity if you:
- Worry about your own spending habits with a sudden windfall
- Want a guaranteed, inflation-adjusted income stream for 30 years
- Prefer simplicity over managing a large portfolio
- Want built-in protection against bad investments, scams, and pressure from others
Watch the clock. The decision is not open-ended. Lotteries set strict deadlines for choosing — in some jurisdictions you have as little as 60 days from the draw date to elect the cash option, after which you may be locked into the annuity permanently. Check your lottery’s official rules immediately after a win.
Common Myths About Lottery Payouts
“The annuity pays less than the jackpot.” No — the annuity pays the full advertised amount. The lump sum is the discounted present value, not the other way around.
“You can change your mind later.” The election is final once made through the lottery. (In some places you can later sell annuity payments to a purchasing company through a court-approved process, but usually at a steep discount.)
“The lump sum is always smarter because you can invest it.” Only if you actually invest it wisely and consistently. The math favors the lump sum at reasonable market returns — but the behavioral reality favors the annuity for most people.
Frequently Asked Questions
How much of a lottery jackpot do you actually get with the lump sum?
Typically around 50–60% of the advertised jackpot before taxes, varying with interest rates. After federal and state taxes, a large jackpot’s lump sum often nets roughly one-third of the advertised amount.
Is the lottery annuity a good investment?
The annuity is not really an investment — it is a guaranteed payout schedule. Its implied growth rate is conservative. Whether it “beats” investing the lump sum depends on the returns you could earn and, honestly, on your behavior.
Do annuity payments continue if the winner dies?
Yes. Remaining payments go to the winner’s estate or named beneficiaries according to the lottery’s rules and the winner’s estate plan.
Which payout is better for taxes?
The annuity spreads the tax burden across decades, which can modestly reduce the lifetime tax bill. The lump sum concentrates it all in one year at the top rate. Neither option avoids taxes.
Can lottery winners stay anonymous?
It depends on the jurisdiction. Some lotteries and states allow winners to claim through a trust or LLC to protect their privacy; others require public disclosure. Check your local lottery’s official rules.
Lottery payouts are exciting to think about, but the odds of winning a jackpot are extremely long — for example, the published odds of winning the Powerball jackpot are about 1 in 292 million. Play for entertainment, set a budget, and never spend money you cannot afford to lose.
Pingback: How Lottery Jackpots Grow: 7 Proven Rollover Facts