When a lottery advertises a jackpot of hundreds of millions, that headline number is almost always an annuity figure, not a pile of cash waiting in a vault. This guide has lottery annuity payments explained in plain terms: what an annuity is, how the payments are structured, how it compares with taking a single lump sum, and the deadlines and tax points every jackpot winner needs to understand. The key point up front: an annuity spreads the prize over many years, while the lump sum gives you a smaller amount immediately. Neither choice is automatically right, and the decision is usually final. Please note: this article is general information only, not financial advice, and it concerns games for adults — you must be 18 or older to play, and lotteries should always be played responsibly.
Table of Contents
- What Is a Lottery Annuity?
- How Lottery Annuity Payments Work: The 30-Payment Structure
- Why the Advertised Jackpot Is Bigger Than the Cash Option
- Lottery Annuity Payments vs Lump Sum: Side-by-Side Comparison
- The 60-Day Decision Window
- Taxes on Annuity Payments
- What Happens to Annuity Payments If the Winner Dies?
- Which Lotteries Offer Annuities?
- Common Mistakes Winners Make With Annuities
- Video: What a Jackpot Is Really Worth
- Frequently Asked Questions
- Conclusion
What Is a Lottery Annuity?
A lottery annuity is a way of paying a jackpot prize in instalments over a long period, rather than all at once. The lottery operator takes the cash value of the prize pool — the money actually collected from ticket sales for that jackpot — and invests it in government-backed securities. Those securities mature on a schedule that funds one payment per year for the winner. Added together, those annual payments equal the advertised jackpot amount. So when you see a headline jackpot, you are looking at the total of all future annuity payments, not the amount of cash available today.
How Lottery Annuity Payments Work: The 30-Payment Structure
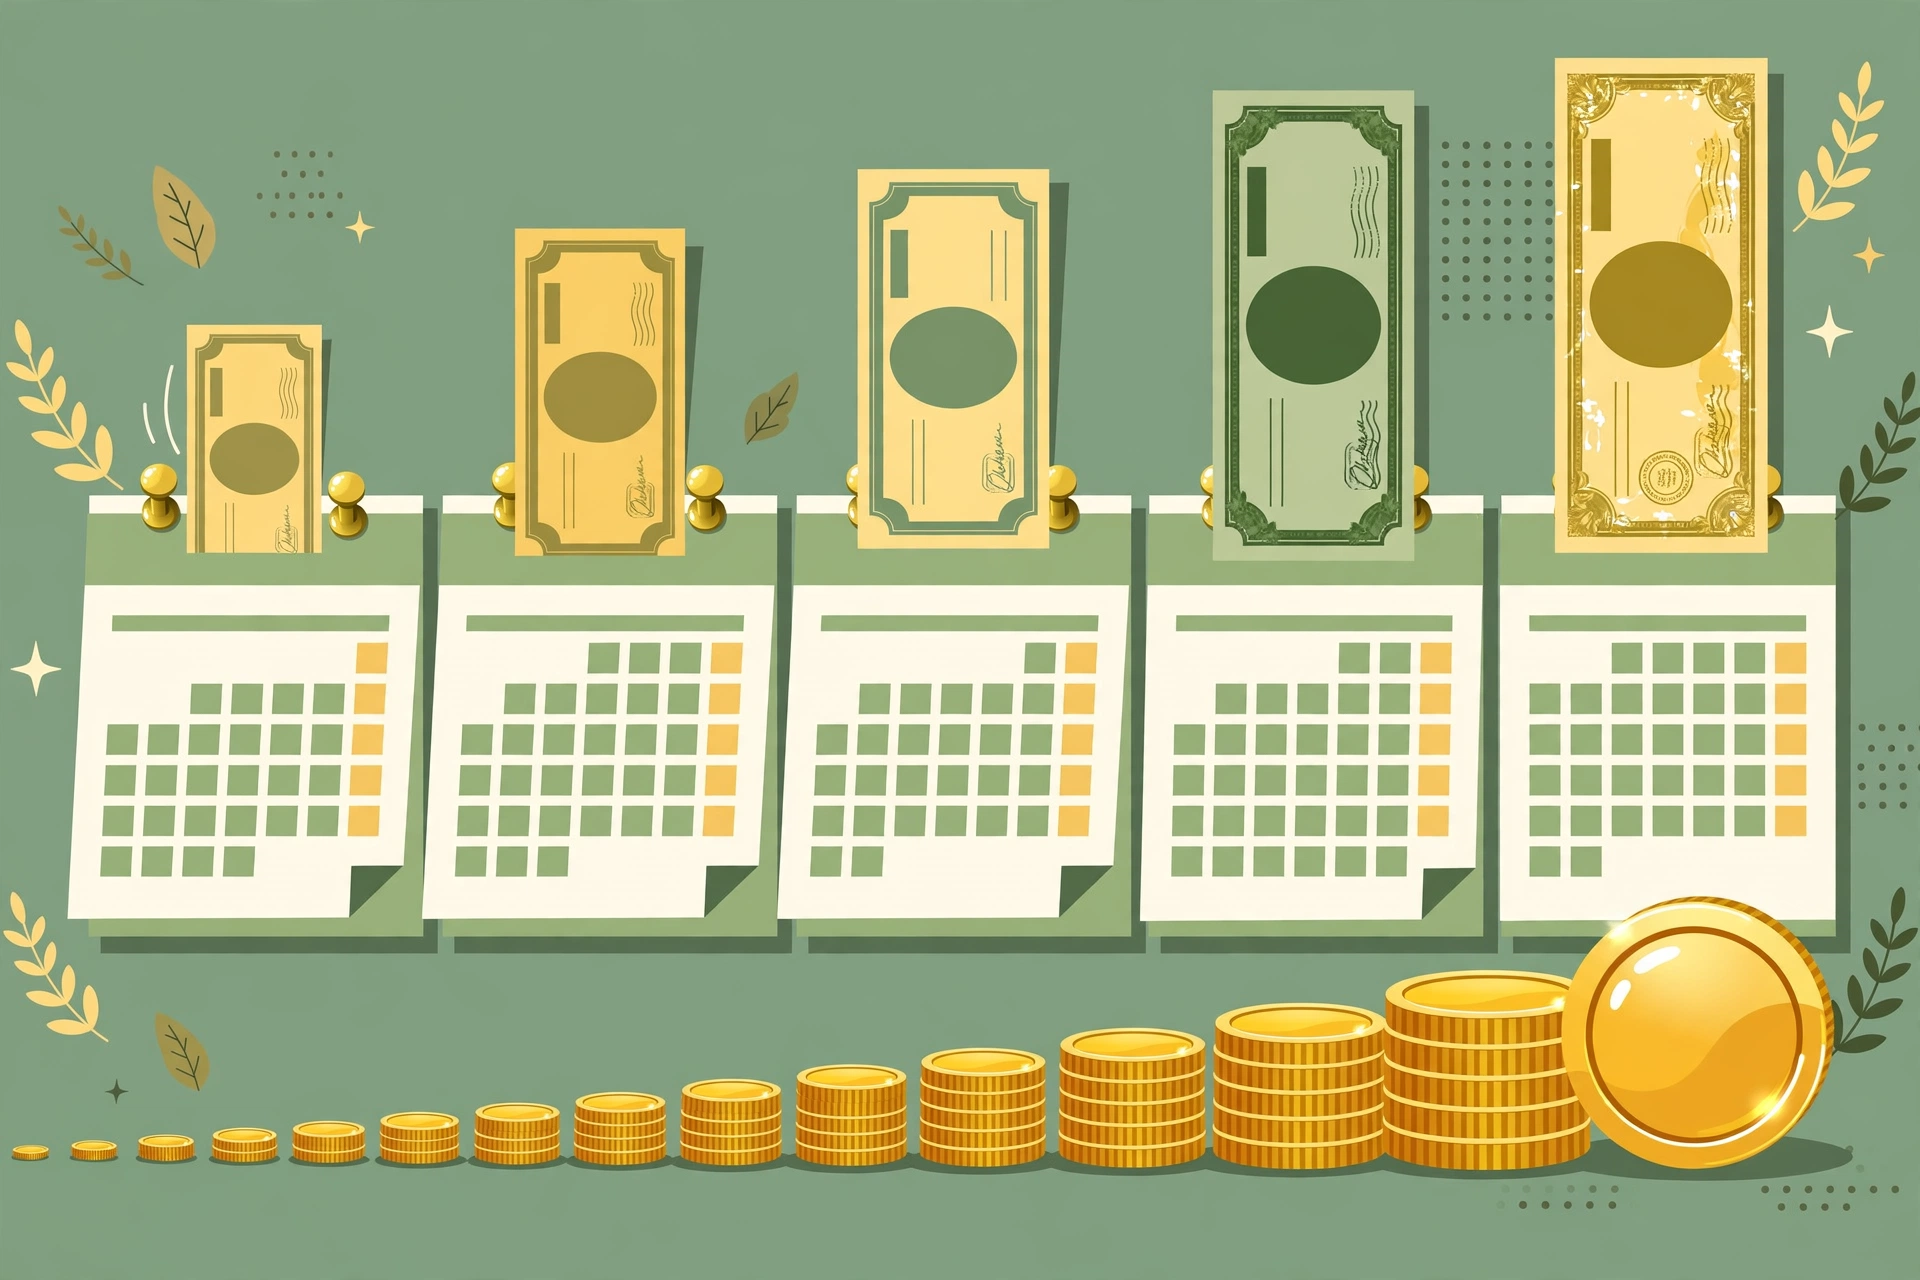
The best-known example is the American game Powerball. According to Powerball’s official FAQs, a jackpot winner who chooses the annuity receives one immediate payment followed by 29 annual payments, for 30 payments spread over 29 years. Crucially, the payments are graduated: each annual payment is 5 percent larger than the one before it. That means the first payment is the smallest and the last payment is the largest, which helps the payments keep pace with inflation over nearly three decades. Mega Millions uses the same 30-payment structure. Once the annuity begins, the payment schedule is fixed and cannot be renegotiated or switched to a lump sum later.
Why the Advertised Jackpot Is Bigger Than the Cash Option
The gap between the advertised jackpot and the cash option surprises many people, but it is not a tax deduction or a fee. The cash option is simply the amount of money actually sitting in the prize pool on the day of the draw. The annuity total is larger because it includes decades of interest that the invested prize pool will earn over the payment period. As a rough rule of thumb, the cash option for a large American jackpot is often around 45 to 50 percent of the advertised annuity figure, although the exact percentage changes with every draw and with interest rates. Understanding this distinction is the single most important step in reading any jackpot headline sensibly.
Lottery Annuity Payments vs Lump Sum: Side-by-Side Comparison
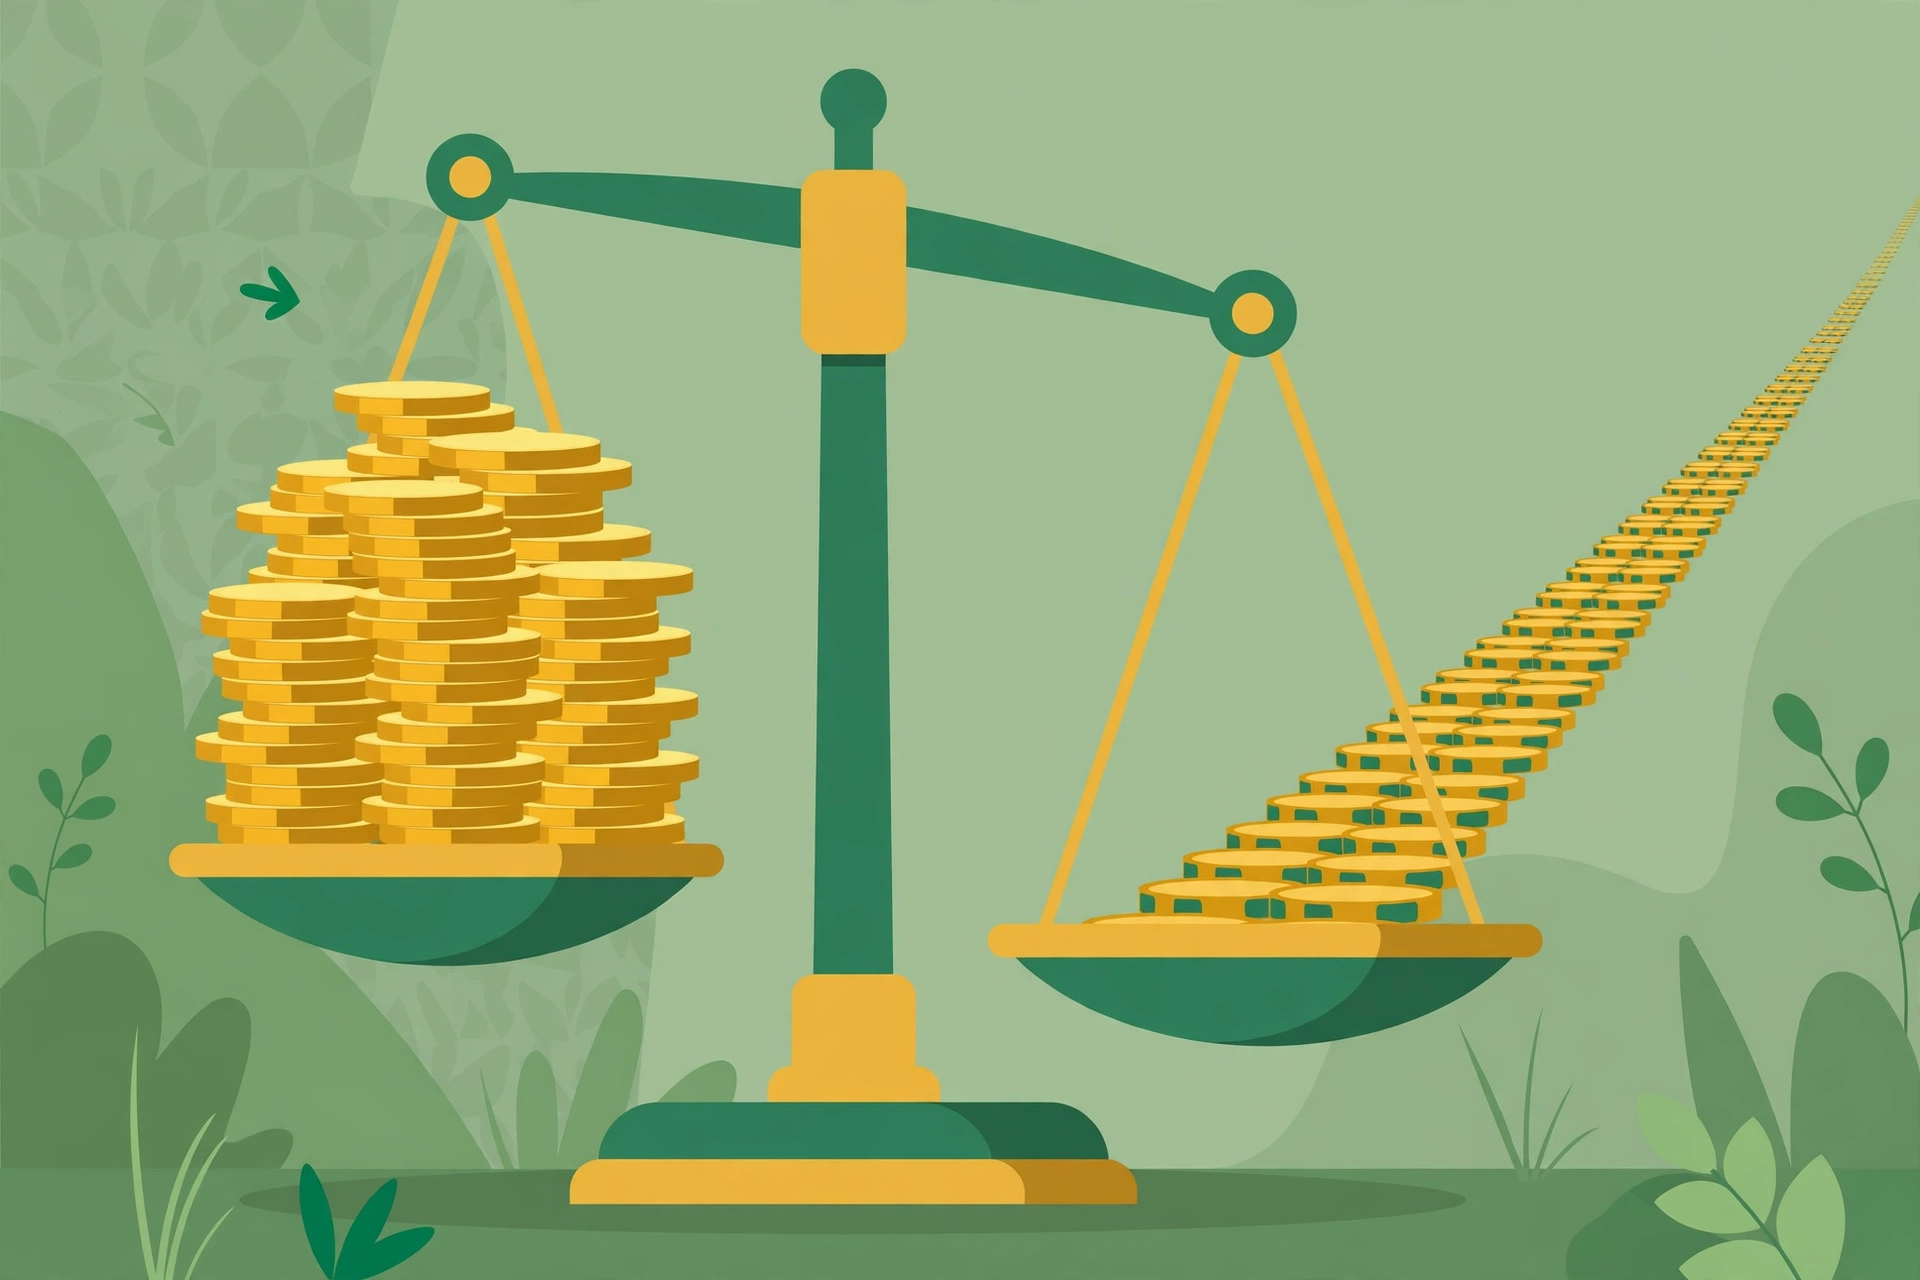
The lump sum gives you immediate control. You receive the full cash value in one payment, and you can invest, spend, donate, or manage it as you wish. The trade-off is that you give up all the future interest built into the annuity, and you face a very large tax bill in a single year. The annuity gives you the full advertised amount over time, with a predictable, rising income stream and tax spread across many years. The trade-off is loss of flexibility: you cannot access future payments early, you cannot change your mind, and inflation and life changes over 29 years are hard to predict. Winners who worry about overspending often prefer the discipline of annual payments, while winners with investment experience or immediate plans for the money often prefer the lump sum. There is no universally correct answer, which is why independent financial advice is so commonly recommended before claiming.
The 60-Day Decision Window
In Powerball and Mega Millions, jackpot winners do not have to choose between cash and annuity when they buy a ticket. Instead, they generally have 60 days from the date of the winning draw to tell their state lottery which option they want. If they do not make an election within that window, the annuity is applied by default. This deadline is separate from the overall prize claim deadline, which varies by state and can be much longer — for more on those time limits, see our guide to lottery prize claim deadlines. Because the choice is irreversible, winners are usually advised to use the window to get professional advice rather than rushing to the lottery office on day one.
Taxes on Annuity Payments
Taxes apply to both options, but the timing differs. In the United States, lottery winnings are treated as ordinary income. Federal withholding of 24 percent applies to prizes over 5,000 dollars, and winners in the top tax bracket may owe more when they file, with the top federal rate currently 37 percent for high incomes. State taxes vary widely: some states tax lottery prizes heavily, while others do not tax them at all. With a lump sum, the entire tax bill lands in one year, which can push the winner into the highest bracket. With an annuity, tax is paid gradually, year by year, on each payment as it arrives. This spreading effect is one of the annuity’s genuine financial advantages, although it does not remove the tax obligation. Tax rules change over time and differ by jurisdiction, so this section is general information only, not tax advice.
What Happens to Annuity Payments If the Winner Dies?
A common worry is what happens to the remaining payments if the winner passes away before the schedule ends. In general, the remaining annuity payments become part of the winner’s estate and continue to be paid to the estate or to beneficiaries as determined by the estate or a court. The exact handling depends on the game’s rules and local law, which is another reason winners are advised to sort out estate planning as part of the claiming process. If you are claiming as part of a group, the rules can be more complex still — our guide to lottery syndicates explains why written ownership agreements matter before a claim is made.
Which Lotteries Offer Annuities?
Annuities are mainly a feature of large American draw games, above all Powerball and Mega Millions. By contrast, most European lotteries pay prizes as one-time lump sums: Eurojackpot and EuroMillions winners receive their prize in a single payment, and the UK National Lottery likewise pays lump sums. Some games offer a different kind of annuity altogether, such as prizes structured as a fixed annual amount for life or for a minimum number of years, rather than a jackpot split over 30 years. The important lesson is to check the specific game’s rules before assuming either option exists — the payment structure is part of the game’s published rules, not something a winner can negotiate afterwards.
Common Mistakes Winners Make With Annuities
The most frequent mistakes are rushing the election, assuming the annuity total equals cash in hand, and forgetting that the schedule cannot be changed. Another is ignoring the tax picture: winners sometimes spend the first payment as if it were tax-free, only to face a large bill later. Finally, some winners tell too many people about the win before claiming, which creates pressure and security risks — our guide on whether lottery winners can stay anonymous explains how publicity rules differ by jurisdiction. The safest sequence is widely agreed: secure the ticket, get advice, make the election within the deadline, and only then claim.
Video: What a Jackpot Is Really Worth
This video breaks down why the advertised jackpot is not the amount a winner actually receives, including the lump sum versus annuity choice:
Frequently Asked Questions
Q1. What are lottery annuity payments?
A1. Lottery annuity payments are jackpot prizes paid in annual instalments over many years instead of a single payment. In Powerball and Mega Millions, the annuity is 30 graduated payments over 29 years, adding up to the advertised jackpot.
Q2. How much bigger is each annuity payment?
A2. In Powerball, each annual payment is 5 percent larger than the previous one. The first payment is the smallest and the final payment, 29 years later, is the largest.
Q3. Why is the cash lump sum smaller than the advertised jackpot?
A3. The advertised jackpot includes decades of projected interest on the invested prize pool. The cash option is the actual money in the prize pool today, so it is always lower — often around half the headline figure.
Q4. How long do winners have to choose between annuity and lump sum?
A4. In Powerball and Mega Millions, winners generally have 60 days from the winning draw to elect their payment option. If no election is made, the annuity applies by default.
Q5. Can you switch from an annuity to a lump sum later?
A5. No. Once the annuity schedule begins, it is fixed. Winners cannot convert future payments into a lump sum through the lottery, which is why the initial decision matters so much.
Q6. Do all lotteries offer an annuity option?
A6. No. Annuities are mainly offered by large American games. Most European lotteries, including Eurojackpot and EuroMillions, pay prizes as one-time lump sums, so always check the specific game’s rules.
Conclusion
Lottery annuity payments are a simple idea with big consequences: the same jackpot can arrive as one large cheque or as 30 rising payments spread over 29 years. The annuity delivers the full advertised amount and spreads the tax bill, but locks you into a fixed schedule. The lump sum gives you freedom and control, but a smaller total and a single-year tax hit. Whichever option a winner leans towards, the decision deserves time, professional advice, and a clear head — and it should be made well within the 60-day window. And for everyone else, the annuity is a useful reminder that jackpot headlines describe a decades-long payment plan, not instant cash. Remember: you must be 18 or older to play, and lotteries are entertainment, not an income strategy — play responsibly, within a budget you can afford.